When investing in a Fixed Deposit (FD), most people focus on the FD Interest Rates and capital safety. Yet, an equally important decision lies in choosing how you receive the interest.
Should it accumulate and grow until maturity, or be paid out regularly to support your expenses? Cumulative and non-cumulative FDs are designed to meet different financial needs.
The right choice often depends on whether you prioritise wealth accumulation or steady cash flow.
What is a Cumulative FD?
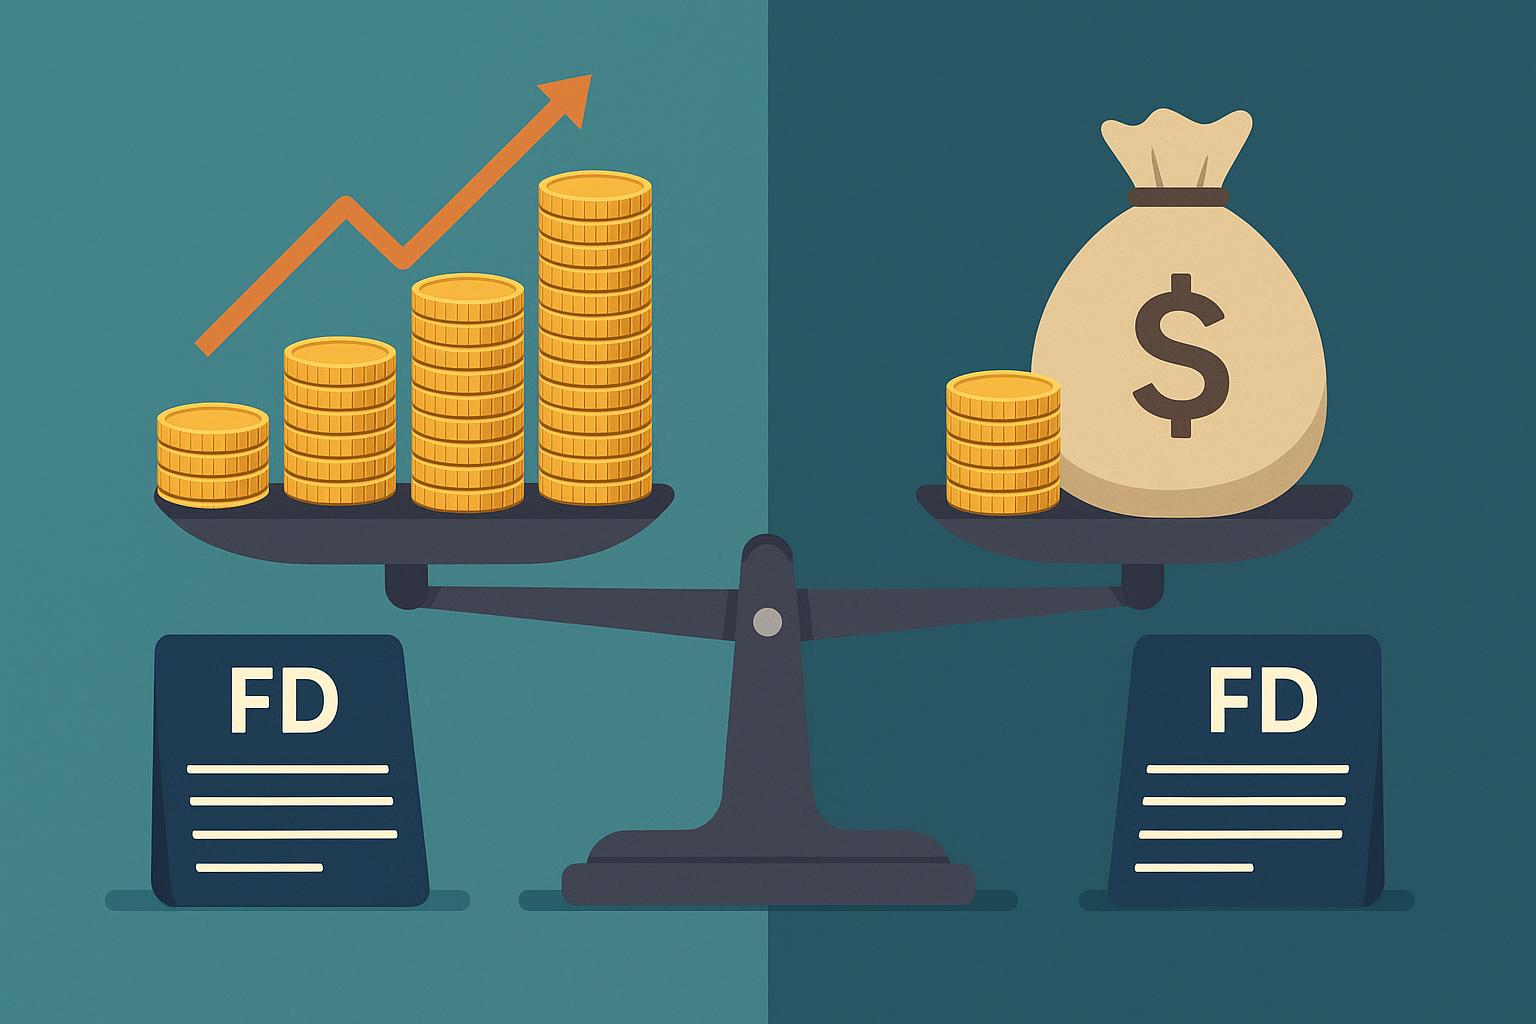
A cumulative Fixed Deposit (FD) is a type of deposit where the interest earned is not paid out periodically. Instead, it is compounded at regular intervals and paid along with the principal at maturity.
This means the interest earns additional interest over time, potentially enhancing overall returns. For example, if you invest ₹1,00,000 for three years, the interest accumulates and compounds, and you receive a lump sum at the end of the tenure. Using a Fixed Deposit Calculator can help estimate the maturity value.
What is a Non-Cumulative FD?
A non-cumulative Fixed Deposit (FD) is a deposit in which interest earned is paid out at regular intervals rather than being added back to the principal. You can typically choose to receive interest monthly, quarterly, half-yearly or annually.
Since interest is paid periodically, it is not compounded as it is in a cumulative FD. If the interest is withdrawn as it is credited, the maturity amount usually consists only of the original principal.
For example, if you invest ₹1,00,000, the interest may be credited to your bank account every month. Non-cumulative FDs are often considered suitable for retirees, individuals seeking a steady income, or those looking to supplement their salary.
Key Differences Between Cumulative and Non-Cumulative FDs
| Basis of Comparison | Cumulative FD | Non-Cumulative FD |
|---|---|---|
| Interest Payout | Interest is paid at maturity along with the principal amount. | Interest is paid out periodically: monthly, quarterly, half-yearly or annually. |
| Compounding Benefit | Interest is compounded at regular intervals, which may potentially increase the overall maturity value. | Interest is generally not compounded when withdrawn regularly, as payouts are made at fixed intervals. |
| Ideal For | Often considered suitable for individuals aiming for wealth accumulation over time. | May suit individuals seeking regular income generation. |
| Liquidity & Cash Flow | Does not provide regular cash flow during the tenure. | Offers predictable periodic income, supporting ongoing liquidity needs. |
Which One Should You Choose?
The choice between cumulative and non-cumulative FDs largely depends on your financial situation, income pattern and overall objectives.
If you have a stable source of income and aim to grow your savings over time without needing immediate payouts, a cumulative FD may be suitable due to its compounding feature. It allows the interest to accumulate until maturity, which could potentially enhance the final amount received.
On the other hand, if you require a monthly income to manage household expenses or supplement your earnings, a non-cumulative FD could be more appropriate, as it provides periodic interest payouts.
For short-term goals, comparing payout flexibility and tenure options may also be helpful.
Before making a decision, it is advisable to carefully evaluate your cash flow needs, financial goals, investment horizon and tax implications.
Conclusion
Ultimately, the choice between cumulative and non-cumulative Fixed Deposits comes down to your income needs and financial goals. If you aim to grow your wealth steadily without needing regular payouts, cumulative FDs are more suitable. On the other hand, if you prefer a regular flow of interest to cover expenses, non-cumulative FDs are the practical choice.
Assessing your short-term requirements alongside long-term plans can help you choose the option that best fits your financial lifestyle.